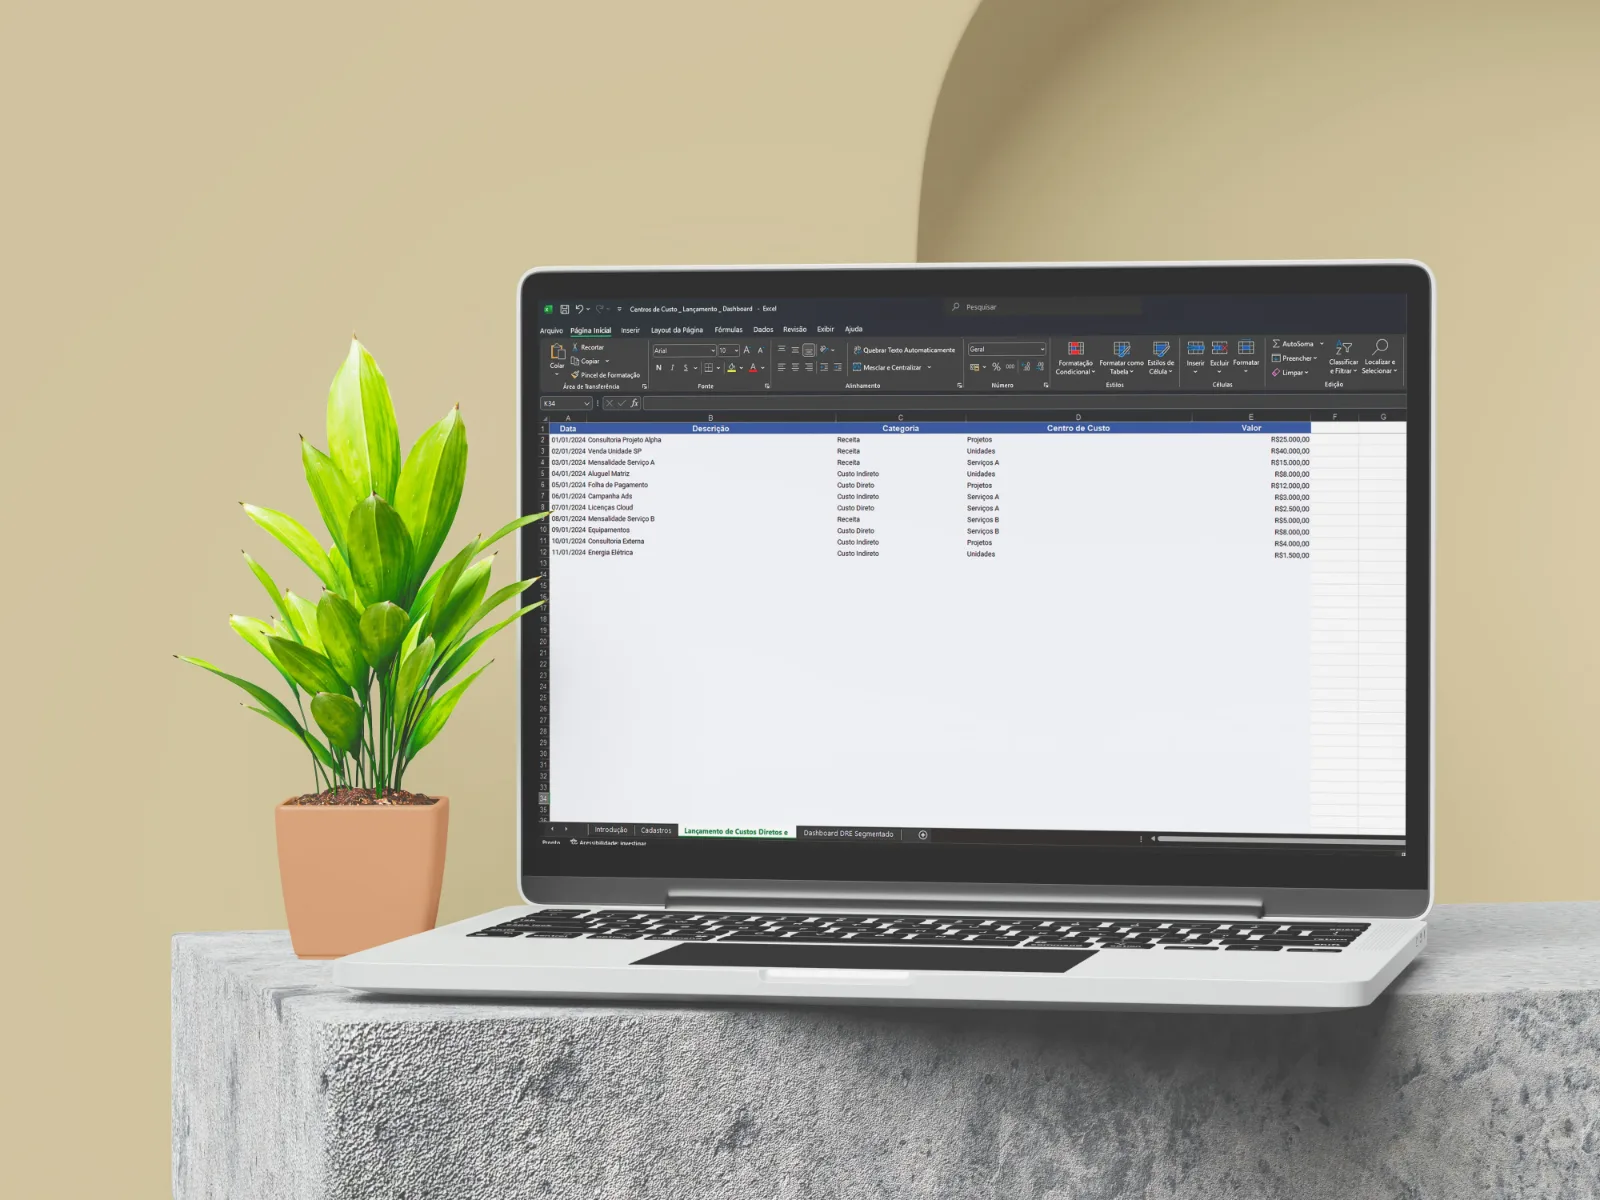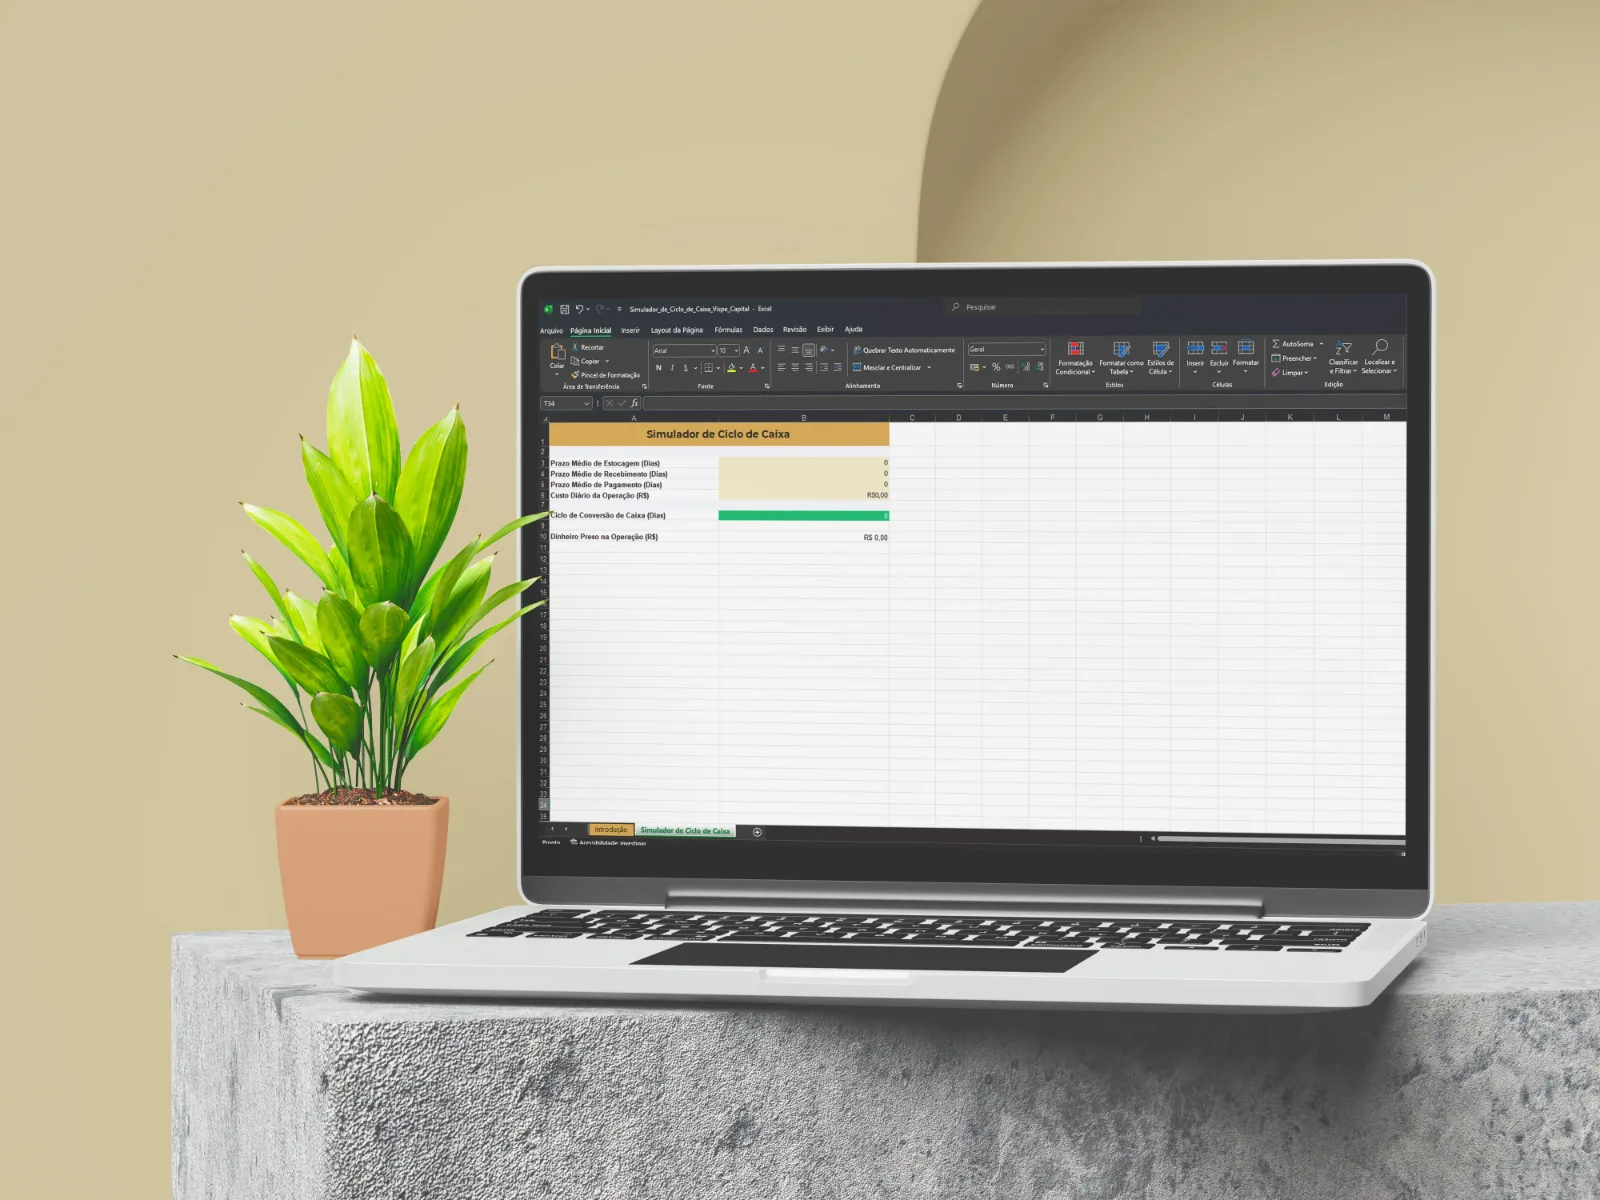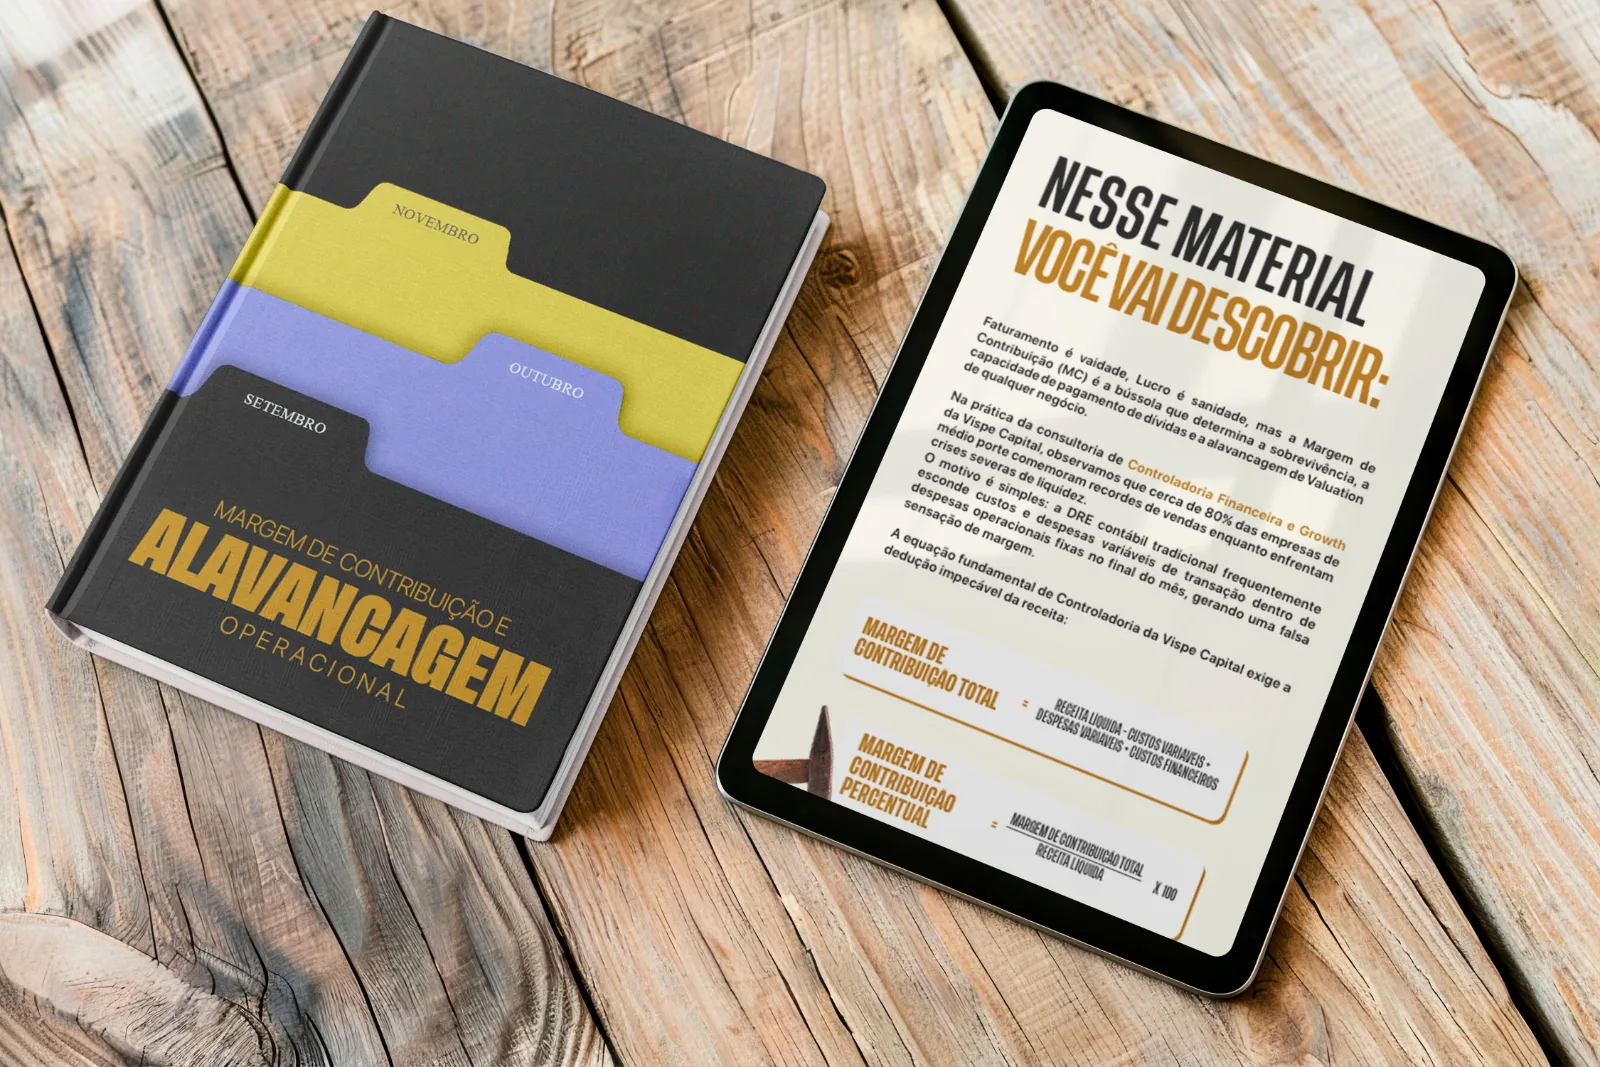
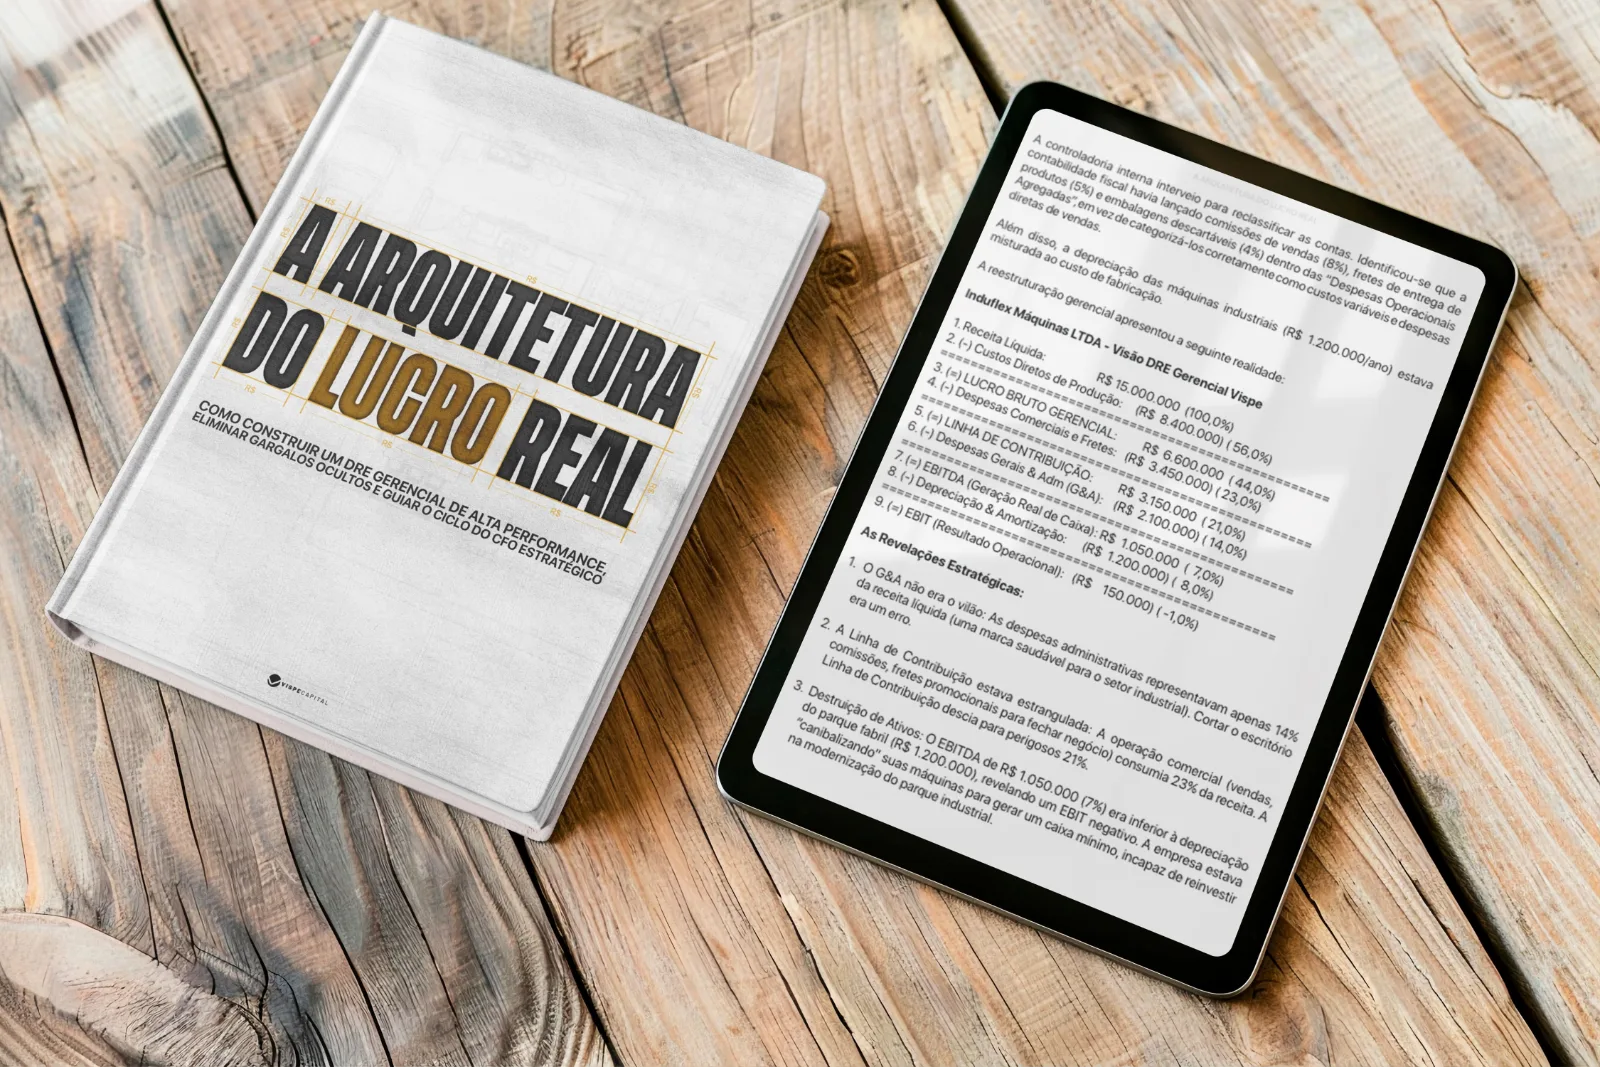
Knowing that the accounting income statement isn't useful for decisions is not the problem. The problem is knowing where cash is bleeding first, how to separate costs from expenses and how to turn your income statement into an equity engine. The Architecture of Real Profit solves that.
What's inside
- A 20-step management cascade
- Accounting vs. management income statement diagnosis
- Separating costs, selling expenses and G&A
- Real EBITDA and valuation calculation
- Reconciliation with final cash flow
- A 5-minute reading protocol
Designed for ongoing use, not a one-time read
Each chapter gives a clear diagnostic view to track progress and a step-by-step structure with checklists to apply to your routine. Financial priorities don't move in a straight line: you can adjust your management income statement to your business's stage and size.
The distinction between economic margin and treasury balance is the most important aspect: some metrics assess sales efficiency, while others require a cash review to keep the company healthy and capitalized.
- Gross margin (COGS): Frequency: Monthly · Priority: High
- Contribution line & CAC: Frequency: Quarterly / Monthly · Priority: High
- Operating EBITDA margin: Frequency: Monthly · Priority: High
- Financial result & fees: Frequency: Monthly · Priority: Medium
- Final cash variable (CAPEX): Frequency: Weekly / Monthly · Priority: Critical